01Flexible
Conventional
An option for a primary residence, second home, or investment property. Down payment and requirements vary by property use and borrower profile.
Every person has a different story, goals, and path. Whether you want to achieve the dream of owning a home or grow your investments, my purpose is to help you understand your options and move forward with a clear, approachable strategy designed around you.
We explain the available paths in a clear and simple way.
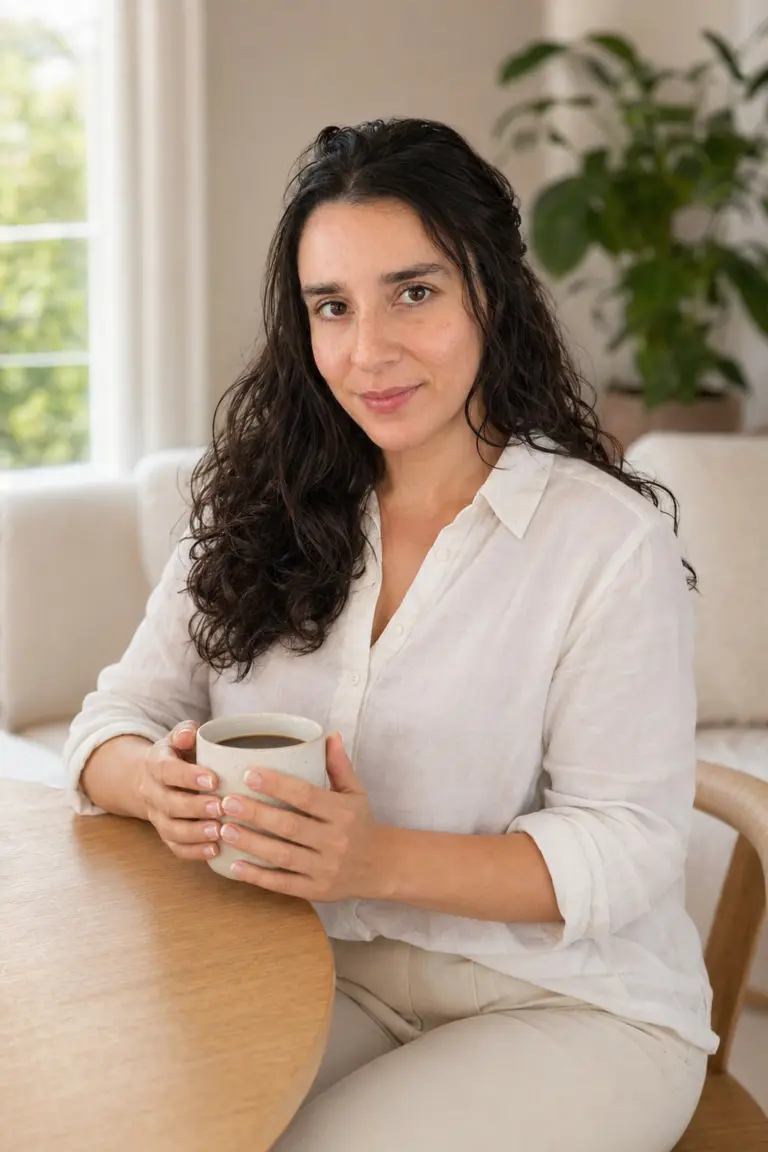
Real people behind your process
I’m Mayra Curbelo, and my purpose is to help you build wealth in Maryland clearly and without unnecessary complications. Whether you are looking for a home for your family or planning your next commercial investment, I take the time to listen to your story and understand your real goals.
Together, we create a financial strategy tailored to you, explained step by step in English or Spanish, so you can make each decision with confidence and peace of mind.
“I stay with you from our first conversation through closing, guiding you step by step so you know what comes next and have professional support throughout the process.”
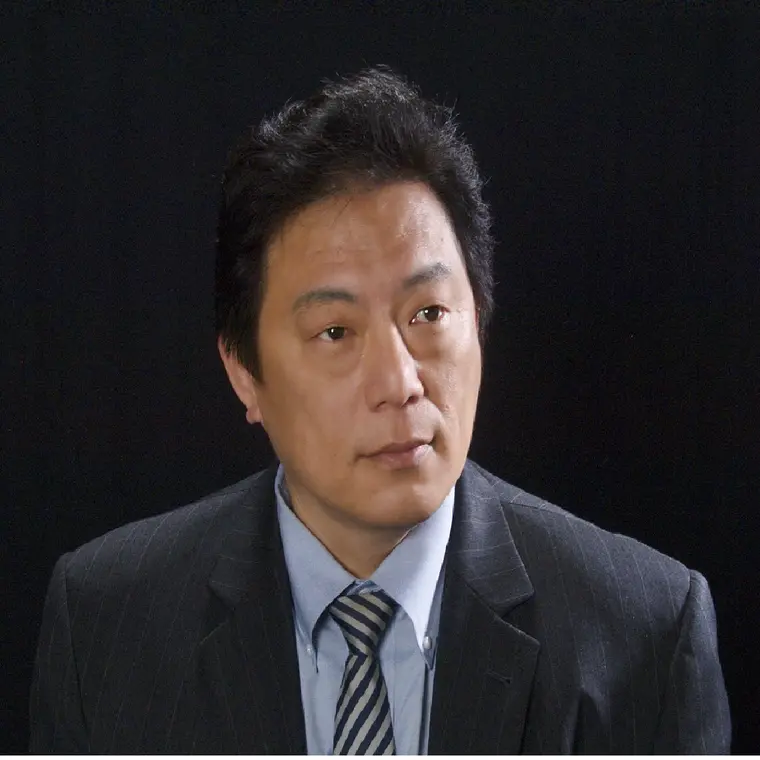
The backing behind your process
Stanley brings extensive experience in reviewing scenarios, comparing loan programs, and working with different lenders. His experience is part of the strength of United Mortgage Plus: a team that shares knowledge, evaluates each situation from different perspectives, and works together to identify well-considered alternatives. Mayra works with you directly throughout the process, combining personalized guidance with the support of an experienced team.
Options for different paths
Not everyone reaches their goal in the same way. That is why I organized the options into four simple categories to help you recognize which paths we could explore based on your goals.
Familiar options that generally verify income, credit, debts, and funds with standard documentation.
These include Conventional, FHA, VA, and USDA. Each program has its own requirements.An option for a primary residence, second home, or investment property. Down payment and requirements vary by property use and borrower profile.
Insured by the FHA. It may offer more flexible credit guidelines and a low down payment. Mortgage insurance and FHA and lender requirements apply.
For eligible veterans and service members. It may finance up to 100% with no down payment and has no monthly mortgage insurance. Eligibility and other requirements apply.
For a primary home in an eligible rural area. It may finance up to 100% with no down payment when the household, property, and income qualify.
* About VA and USDA: “up to 100% financing” means some eligible borrowers and properties may not require a down payment. It may not cover closing costs, prepaid items, appraisal gaps, or other required funds. Subject to application, eligibility, credit, income, occupancy, appraisal, underwriting, program guidelines, and availability; this is not an approval or loan commitment. VA.gov · USDA Rural Development
Paths for people whose income documentation or situation does not fit a traditional loan.
Options may consider ITIN / Tax ID, bank statements, P&L, rental income, construction, or international documentation.Options for people who file taxes with an ITIN instead of a Social Security number. Down payment and documentation depend on the program.
For self-employed borrowers and business owners. Bank deposits may be used to evaluate income instead of relying only on tax returns.
For business owners. A profit-and-loss statement shows how the business is performing. It generally must be prepared or validated by a Certified Public Accountant (CPA).
For investment properties. It compares the property's expected rent with its monthly mortgage payment instead of relying mainly on your income.
Ask about this optionFinances the construction or rehabilitation of a home. Funds are generally released in stages as work progresses, and terms depend on the project and lender.
For eligible foreign buyers seeking to finance Maryland property. Documentation, assets, and down payment depend on the program.
Some products are not defined simply as Traditional or Alternative. They may help you use home equity or address a specific financing need.
Before choosing, I help you understand and review your options.Helps eligible buyers cover part of the down payment and, depending on the program, some closing costs. It may be offered as a grant or additional loan.
Explore buying your next home before selling your current one through a strategy based on available equity and your financial capacity.
Ask about this optionA credit line secured by your available home equity. You can use funds within the approved limit; the rate and payment may change.
Temporary financing that helps cover the time between buying one property and selling another. It is generally short term.
Combines two or more financing sources on a property to reach a specific structure, subject to available equity and lender guidelines.
For eligible homeowners, it converts part of a home's equity into funds. The loan is repaid later, and property taxes, insurance, and maintenance must remain current.
Financing for properties, businesses, or investment projects that do not work like a residential mortgage.
The review usually focuses on the property, the project, and its ability to generate income.For offices, retail spaces, warehouses, and multifamily buildings with five or more units. The property and its income often play an important role.
Private capital, generally short term, for certain investments or projects. It often focuses on property value and may carry higher costs.
Let’s clear up your questions in a free 20-minute conversation.
Program availability and terms may change. References to FHA, VA, or USDA describe program types and do not imply government affiliation or endorsement of Mayra Curbelo, Tu Casa To Go, or The Rate Factory LLC.
Simple, human, and at your pace
Reserve a secure initial consultation to talk about what you want to achieve. I handle your information with care and confidentiality and use it only to understand your situation and guide your first steps.
Together, we evaluate the alternatives available in the market. I explain the solutions that can truly benefit you in clear, simple terms while looking after both your budget and your peace of mind.
When we find the option you feel most comfortable with, we get started. We begin the pre-approval process, and I guide you step by step through the necessary documentation.
Additional documents may be required during the process. Read the Privacy Policy →
Share your initial situation so we can prepare your free preapproval appointment.
Click or tap hereI’m ready to qualifyInformation worth saving, sharing, and revisiting
Mortgage Information Center · Learn before you decide
Buying or refinancing feels simpler when you understand the words, documents, and decisions along the way. Explore short guides, a clear glossary, and practical articles so you can enter each conversation with greater confidence. Content is educational and does not replace an individual review or legal, tax, or financial advice.
Financial and process terms explained so you can recognize them with confidence.
Learn what may be requested, why it is used, and what it means.
General guides to disclosures and important questions to understand before signing.